Showing posts with label investing. Show all posts

Sunday, 19 April 2020

8th day small profit that helps me to keep going in the competition


After a successful week and most importantly from recovering almost $6k, I wanted to consolidate my positive results. My desire was to build up the account to be able to deal with possible drawdowns.


6B 06/20 day chart
6B 06/20 future


Monday was a very quiet day in comparison with the previous days. The British Pound jumped 
almost 50 pips early in the morning but after that, the USD recover its strength. This changed again after midday when the price started to rise again.


6B 06/20 13/04/2020
6B 06/20 trade chart

I realized that I had a notification. My algo bought 5 lots during a retracement. In the beginning, it went against me, but it quickly recovered. It didn’t make a big movement but was more than enough to finish the day with a small profit. I personally don’t like to take positions at that time on the day because the algo closes the positions around 17:00. To be honest, it doesn’t matter if I like it or not, what I need to do is check that it’s statistically significant.  


Profit and new account balance


Trade 13/04/2020
Trade 13/04/2020

As I said, it was a small profit, but these kinds of days help to build up the account. The maximum adverse excursion was small. The algo closed the position close to the maximum favorable excursion which I’m very happy about. I have the feeling that I’m leaving a lot of money on the table. I am allowed to make one change in the algo during the competition and I’m seriously considering adding a take profit. These will reduce the time in which the algo maintains positions open and more importantly it will secure profits. On the other hand, it won’t let the profits run as much this is why I need to carefully check before I implement the change.


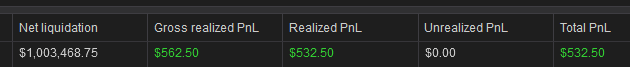
Account balance and realized PnL


The account balance at the end of the day was $1003468.75. Even if it’s not real money, I feel very well because the algo is behaving as I expected and it’s able to recover from drawdowns.

Thanks for reading this post!

Wednesday, 8 April 2020

Robotrader2020, algorithmic trading competition


I decided to participate in Robotrader and I believe that is worth to share my experience here.

I consider Robotrader as one of the referents in algorithmic trading education in Spain. It offers a series of lectures or seminars with some of the best professionals in algorithmic trading, investment banking, and technology.  In addition, it holds a competition in which the participants need to create an algo to trade automatically for two months. This is the 10th edition and it’s been a great so far.

The main purpose is to introduce the world of trading and automatic investing to students and invite them to do it using different programming languages.
I think that it is a great initiative even if you have knowledge about investing in financial markets. It is very difficult to find professionals with knowledge in both areas. To be honest, it helps you to understand how difficult is to try to merge one traditional area like trading with technology. Obviously, it depends on each student, some of them will focus on high-frequency trading systems while others will focus in a more traditional trading system.  One of the things that I like the most is that it challenges you on the technology side. I mean, it’s not only programming the algo. It involves making research, try to understand how the markets move, designing the algo, backtesting, optimizing, choosing the right money management system, and putting this in production through a paper trading account. And when you think that you are done…  don’t forget to deal with connectivity because if you don’t connect, the orders won’t be sent to the exchange.


I will be sharing my experience during the competition. It started last week so I have a couple of articles to post.

Finally, I would like to thank the Universidad Politecnica de Madrid (and everyone that is supporting this event) for this initiative.  Please see this link if you want to have a look:


Thanks for reading this post. 

Wednesday, 5 September 2018

Simple trading system, does it work in the Nasdaq?

Introduction

There are so many trading styles and the traders can take their decisions from technical analysis, important levels, value investment, quantitative analysis, price movement, and order book study. Some of them combine more than one method at least to have another point of view or to have another idea generation source.

Nowadays, it's easy to find resources for trading. There are plenty of resources online, such as videos and courses. If you are more traditional, you can search for books and see what the people are saying about them.

Some of the most successful traders are known for being contrarians. What does this mean? Maybe they are aware of how powerful the trends could be, however, they are not investing for the long term. They are looking for a quick profit in a short period of time (depends about the how big is the position, who is executing and what are the targets, it can last from a few seconds to less than 3 months).  How do they act? Basically, if a stock or a future has been raising for a while and has a strong trend, they can consider that the product is overvalued and that it will revert to the moving average or at least it will revert enough to make a profit.

The idea

Now, we know what they do. I always thought about it. One of the problems is the timing when I should enter into a trade like that. There are so many statistical methods that you can apply to that. It can be based on the number of days (imagine that the stock has been raising for the last 60 days and you think that every “X” days, there is a retracement), it can be based on the price change (that you can consider it overvalued), it can be a combination of both. We can see that creativity is another part of the trading research. Probably, I will write a post about the whole process in the future but today we are going to review a simple idea.

The trading system is contrarian so it will consider yesterday % change. If yesterday the stock or the underlying product went up, the system will sell it today. And the other way round, if the stock fell yesterday, the system will buy it today.

Nasdaq


I’ve chosen the Nasdaq index as an example. It represents the technology stocks.

    Nasdaq continuous future, daily, source: TradingView

It hasn’t stopped rising since 2010. I wanted to show the period 2014-2018 that I will study in this article. Considering the strong bullish trend maybe I shouldn´t use a contrarian system. I will show you that one of the most important aspects is the risk management (always combine with a profitable system)

Backtest example

Before we start, I need to explain a couple of things. In my opinion, the market behaves differently when it goes up than when it goes down. The falls usually are very sharp. This is why I decided to choose a tighter stop for the sells. I’ve chosen the stops randomly, the buys have a stop of 4 ticks and the sells have a stop of 2 ticks. Let’s check the results:


                                        Backtesting, own elaboration using R

Good news! The mean is positive which is a good starting point. However, making $9.53 per trade is not enough without considering fees and slippage. The system makes $2190 on the best day. The worst lost is $20. The kurtosis is really high because all the values are concentrated around 0. To be honest, the system only makes money on the 3% of the trades. So it’s not tradable even if it makes 103.65% in four years. It would be great if the system had more entry requirements and the number of trades would be reduced. That way the statistics would improve a lot. The Sharpe ratio isn’t great. 


                                                           Max drawdown, own elaboration using R

Considering that the trading system loses in 97% of the trades, the max drawdown is very good. Obviously, each time that it loses, the amount is very small (around 0.2% of the portfolio)


Trading strategy performance, own elaboration 

We can see the characteristics of the system. A few profitable trades and a bunch of losing trades. The probability of taking the loss is very high with our tight stop losses. In other hand, every time that we are right, we make a lot of money.

Sum up

Sadly, there isn’t a good conclusion for this post. I think that I have a lot of work to improve this system.  In addition, this is not a professional way of running a backtest. We should have a period of time in which we test our idea, another period for optimization and different windows of time to test the optimized parameters. Also, we should always consider broker fees and slippage. The system shown is not tradable but it shows that a sounding risk management system is very important. Another idea that we should take from this post is that even a contrarian system can perform in a market that has a clear trend. I hope you like it.
Have a good trading!


Disclaimer


I wrote this article myself, and it expresses my own opinions that shouldn't be used as a trading advice. Trading carries considerable risk due to the high leverage involved


Monday, 27 August 2018

How to get 1 Million Dollars (or Euros, or British Pounds…)


Introduction

The other day, I had a really interesting conversation with one of my friends. It was the kind of thought that we can have on Sundays. We were wondering how to get one million dollars (or Euros, British Pounds, it's applicable to all currencies)

Discussion

In the beginning, we were saying silly things that come from social media and it's difficult to verify if it's true or not. After that, we briefly talked about real estate. Everything looked great but the high capital required to invest in this kind of asset makes it difficult (without having already saved part of the mortgage)

We follow the main hedge funds, so we started talking about trading legends such as Jim Simons, George Soros, Warren Buffet, Ray Dalio, Steve Cohen, William Ackman and Ken Griffin (The list is really big, they are only a few of the best)


The next table shows the 3-year compound return for some hedge funds:

 Penta Top 100 Hedge Funds, Source: Barrons
                 Penta Top 100 Hedge Funds, Source: Barrons

You can find the whole list on the link below:

This idea was great but considering that some of the strategies used by hedge funds (and asset management, CTAs… ) require big sums of money, it was discarded automatically. In addition, we don´t know wealthy investors and we don’t have any track record.  Another solution is to invest directly in one of these entities, but again, the mínimum investment is pretty high.
At this point, we were aware of the reality but I said that we can get it! The only requirement is commitment and patience (this will be discussed later on)

The model

Before I explain this model I would like to make some assumptions:

  • I consider that the money saved every month is the same for the whole life of the individual.
  • All the savings are for investment purposes.
  • The individual can’t withdraw any money once it´s invested.
  • The return is positive for the whole life of the investment (the return is considered as an annual average return of the investment)
  • The investment is not defined
So basically there is no secret, the idea is based on saving money every month and invest it in the asset that you consider suitable for you. 


The table used for the calculation, own elaboration
       The table used for the calculation, own elaboration

As you can see the table has different columns, let me explain them. The year and the month are in order for charting purposes. The savings is the amount saved per month (in the example is 500 but I´ve done it for 300, 700 and 1000 units of currency every month) The rest of the columns represent a financial calculation to reflect the effect of investment (in that case, I’ve chosen monthly compounding (Amount saved * (1 + Annual return % ) ^ (1/12)) 


 Example of the first 5 months and the last 5 months, own elaboration
     Example of the first 5 months and the last 5 months, own elaboration

This is the same table as the previous one. I want to show the top and the bottom of the table used for the charts that I’m going to explain now. 


Total savings after 40 years without investing them, own elaboration
      Total savings after 40 years without investing them, own elaboration

These are the amount we would have after 40 years (or 480 months) without investing. Obviously, if you save more, you will be wealthier in the future.


Final amount after investing for 40 years, own elaboration
      Final amount after investing for 40 years, own elaboration

This table is really interesting because shows the capital after investing for 40 years. Here we can see why investing is very important to build wealth. Let's say that we can afford to save 300 units of currency per month. After 40 years, we check the account and we can find 2 outcomes depending on if we decided to invest or not. Without investing the savings, we would have 144000 while if we had invested at 5% per year, we would have made 446569,38. Investing generates 3 times more money than only saving (there is risk in every investment and you should check if it’s suitable with you or not) Returning 10% or more per year is not impossible but doing consistently is very difficult. However, if you get it, you will see your investments grow quickly. 


Charts about the lifetime investment for the different average returns and savings levels, own elaboration

  Charts about the lifetime investment for the different average returns and savings levels, own elaboration

Here we can see the effect of compound interest over time. As Albert Einstein said once: “the power of compound interest the most powerful force in the universe”

Now coming back to the title of this post, let’s find out how many months of savings we need to reach 1 million:


Months needed to reach 1000000, own elaboration
      Months needed to reach 1000000, own elaboration

Sadly for the lower saving quantities is not possible to reach this figure or a high return is needed. Sadly there is a high risk involved in strategies that return high return.  For the rest is easier but it’s not an overnight process. At this point, we need patience and keep working hard.

Why only a few percentage of people become as wealthy as in the example?

  • Investing is not as linear as I showed. There are years in which you make a profit and years in which you may lose money or even you can be breakeven.
  • Saving money sometimes depends on a personal situation (There are so many things in life more important than saving a fixed amount every month)
  • At the beginning of your professional career the salary is low and after that, it should adjust according to the experience.
  • After saving “X” amount of money, you can think of relocating to a better property, getting a car or something that won't allow you save as you have been doing until now (maybe your salary has increased enough to cover this expenditure via personal loan but it’s difficult and it doesn’t apply to everyone)
  • The example shown doesn’t apply to everyone because you need to work for the next 40 years.


Conclusion

Even if getting a million is difficult, it’s not impossible. If your personal situation allows you to save and invest every month, the only secret is Commitment and Patience. You need to understand the investments and the risk involved.

All the best!!


Sunday, 19 August 2018

SP500 vs Gold, using their correlation to make a trading strategy (Part 1)


This post is part of a new series in which I will show how to figure out if we can build a strategy using some assets’ correlation. Let me introduce the assets:


S&P500

Mini S&P500 future (continuous contract), daily, Source: TradingView
    Mini S&P500 future (continuous contract), daily, Source: TradingView

The Standard & Poor's 500 is one of the main American stock market index based on the market capitalizations of 500 large companies having common stock listed on the NYSE or NASDAQ. As you can see, this index hasn´t stopped raising since 2011. 

Gold

Comex Gold future (continuous contract), daily, Source: TradingView
    Comex Gold future (continuous contract), daily, Source: TradingView

The Comex Gold is one of the most important futures. You can trade it directly or you can use it to hedge your stock portfolio. Historically this hedge has been successful and has protected the portfolios versus big drawdowns. It´s recommended to have at least a small part of your investments in gold (even if it´s in an exchange-traded fund that tracks this metal)


I reviewed Gold futures and ETF´s last year: Gold Analysis


Spread between SP500 and Gold

Spread between SP500 and Gold futures, daily, Source: TradingView
    Spread between SP500 and Gold futures, daily, Source: TradingView

To simplify the calculation, I decided to make the spread as 1 E-mini S&P500 future minus 1 Comex Gold future. As you can see, the relationship was negative before 2013 because the gold price was higher than the S&P. Since then, this spread has raised almost like the US index. This explains that the different QE programs calmed down the uncertainty (so the investors started buying the S&P and started selling or reducing their gold portfolio)


Introduction to the study

Correlation series

For this part, I chose 4 correlation series (20, 60, 120 and 250 days) that represent different time frames. 


Correlation time frames table, own elaboration
      Correlation time frames table, own elaboration

The main reason for choosing this time frames is to make comparisons and to see if I can work out a strategy in the following posts. 


 S&P500 and Gold correlation series, own elaboration
     S&P500 and Gold correlation series, own elaboration

We can’t get any conclusion from this chart apart that the long-term correlation between S&P500 and gold is negative (the most part of the time).  One of the things I would like to study in the following days is if I can build a profitable system based on the correlation series divergences. For now, I can show the different charts with the asset prices and the correlation (The Y left axis represents the price of the assets and the Y right axis represents the correlation coefficient):


 S&P500, Gold, and  20 days correlation serie, own elaboration
     S&P500, Gold, and  20 days correlation serie, own elaboration

This chart doesn’t show any clear relationship. Another problem is that is a short-term correlation that generates a lot of noise in the signals and it´s difficult to know if it´s worth to check this correlation to trade the spread.


S&P500, Gold, and  60 days correlation serie, own elaboration
    S&P500, Gold, and  60 days correlation serie, own elaboration

The 60-day correlation is smoother than the previous one. I think that we can take advantage of the correlation every time that is above 0, however, a statistical study is required. 


 S&P500, Gold, and  120 and 250 days correlation series, own elaboration
  S&P500, Gold, and  120 and 250 days correlation series, own elaboration

As I said before, we can see that the most part of the time these correlations are below 0. Like in the previous chart we can take advantage of the correlation above 0. In addition, I would be interesting to study a trading system based on the 120 days correlations that trigger a trade every time is under -0.2. In terms of correlation’s divergence, we need to backtest it properly.

Sum up

I’ve chosen these assets because they are really important. The S&P500 reflects the US economy and the Comex Gold can be used as an investment or as a hedge vs the main index in a recession. Sadly this post is an introduction. I will analyze the systems proposed using advanced statistics and some backtests. As a reminder, the systems will be based on the correlation and its divergences. 


#trading #investing #correlation #ES #GC #SP500 #Gold #statistics

Thursday, 28 June 2018

Momentum system


Sometimes we look for a clear trend in the different markets. This can be difficult these days because the volatility is back. I believe that there are many opportunities but you need to adjust the strategy’s timeframe. Obviously, when we see the chart at the final of the day,  it´s easy to see the levels where we should have bought or sold. I would be happy as far as you do this in order to learn the order flow and how the news affected the security. However, you shouldn’t take seriously the important levels of the day (if you are only checking the day instead of a longer timeframe) because anyone knows what is going to happen tomorrow. I wouldn´t like to discourage you if it works for you but in my opinion is like singing “if I were a rich man” without trying to make money.

Why is the data important? Introduction to the system

As I said indirectly in the first paragraph, I don’t know what the asset prices are going to do tomorrow. The most important for me, leaving my thoughts apart, is the historical data. Here is where statistics takes importance. Let’s get biased for a minute thinking that every time that the price is above an indicator (or another variable) we should buy and every time is below the chosen variable we should sell.


Let´s take the Moving Average 9 as this variable and check the probabilities.

                                               Probability table, example own elaboration

Only to sum up, we have a buy signal every time that the opening is above the MA9 and a sell-side every time the opening is below this indicator. This example is not the best one. I wouldn’t publish this screenshot in a book. Apart from this joke, we had 426 buy signals but only 203 days that the future closes above the opening. Investing in a strategy that has 47.7% success ratio doesn´t seem the smartest thing to do but this is where the money management comes! In the case of the sell signals, it's slightly better showing 52.4%.

Backtesting

Before I show the results I would like to confirm that I´ve used the 5-day moving average instead of the MA9.  The main reason is that the performance was better and the drawdown was lower. This test has been done with the FESB historical data (Eurostoxx Banks). The reason why I chose this product is because I thought that it was directional enough to apply the strategy.


                                                  Backtesting statistics, own elaboration using R programming

As you can see the backtesting results are not bad. Each trade generated 6.42 EUR on average. The biggest win was 740 euros which is great considering that we started with 10000 EUR. I used a tight stop loss, only 2 ticks. Even with that, we can see that the FESB is very directional and the stop was hit only on 53% of the trades. The return has been 56.60% in almost 3 years and a half.


      PnL curve, own elaboration using R programming


The most interesting thing is that after the max drawdown (1570 between the 98th day to the 270th day) it has been rising. Obviously, when your portfolio has grown and you are using the same money management and risk management, the drawdowns are smaller than at the beginning. 


                                                      Max drawdown, own elaboration using R programming


Each trade was simulated with 2 lots and the maximum daily loss was 20 EUR (2% of the initial capital)

Sum up

I like analyzing trading systems and I´ve been working on this strategy for a while. I´m surprised about its performance because I expected worse statistics. Surprisingly, the % of successful trades were almost the same as the previous example shown above. This post doesn´t show the real performance because the commisions are not included. I will write a post in the future explaining why the short-term moving averages fit better than the long term in this kind of system. I hope you like it.
Have a good trading!! 


Disclaimer


I wrote this article myself, and it expresses my own opinions that shouldn't be used as a trading advice. Trading carries considerable risk due to the high leverage involved

Sunday, 6 May 2018

European Financials review


Today is the turn of the European Financials. Are these companies in a good shape? Should we wait? We have seen an incredible run since 2009 and the main reason was the quantitative easing programs applied by the different central banks around the world. We can see that the Fed is tightening while the ECB and the BoJ keep running the easing programs. 

Eurostoxx


     FESX (Eurostoxx) continuous future, source: TradingView

As you can see the Eurostoxx has been raising since 2012 with the exception of 2015 and 2016. In this period we saw macro improvements in the European economy apart from the inflation data.

Eurostoxx banks 600

     FESB (Eurostoxx Banks 600) continuous future, source: TradingView

In contrast to the Eurostoxx, the banking index hasn´t shown a continuous growth. After the recovery from 2009, this index fell until 2012. We saw important highs in 2014 that couldn´t be broken in 2015. After that and due to the Chinese Black Monday, this index was falling until the middle of 2016. The last bull run was between 2016 and 2017. At the moment is testing a resistance around 127.00 that worked as a support in the previous year.
At this point, it is difficult to say if the movement will continue to the upside or will look for lows. The earnings picture so far has been mixed. HSBC, Europe’s biggest bank, reported profits matching expectations. On the other side, the French banks' earnings disappointed the market. Societe Generale and BNP Paribas traded lower on Friday due to their earnings report. The general concern in the sector is the rising costs. The monetary policy applied by the ECB doesn´t help the banks. Hopefully, the loan growth should pick up sooner or later.

EUFN iShares MSCI Europe Financial Sector Index

Let’s have a look at this interesting ETF. As a brief explanation, the iShares MSCI Europe Financials ETF seeks to track the investment results of an index composed of developed market European equities in the financial sector. The reason to invest in an exchange-traded fund is to avoid stock picking and taking advantage of tracking a sector in this case with a small cost. These are the portfolio characteristics:


       EUFN (iShares MSCI Europe Financials), source: iShares (Blackrock)

The P/E ratio is not the one that the value investors look for but it’s appealing if you compare with the current market levels. I would like a lower P/B ratio but it´s acceptable. One of the problems with the financial sector is that it´s cyclical, conservative and it’s not as profitable as it used to be. In the case of Europe is even harder to make money at the moment due to the ECB policy. Hopefully, adopting new technologies and AI will bring positive returns to this sector in the future but this is a long-term goal.

This is the current composition of this ETF:


      EUFN (iShares MSCI Europe Financials), source: iShares (Blackrock)

Diversification is one of the ETF advantages. As you can see, these are the top ten holdings on this fund. 


     EUFN (iShares MSCI Europe Financials), source: TradingView

The EUFN tried to rise to 2014 highs in the first weeks of 2018. Sadly this attempt failed and now is down 10% from the highs of the year. This product has been ranging between 14$ and 27$ in the last 8 years.


     EUFN (iShares MSCI Europe Financials), source: TradingView

This chart shows the EUFN prices for the last 3 years. After comparing the last two charts, I consider that buying below the 18 level is interesting for the long term with a take profit in 24. Obviously, you should be able to handle a 20% drawdown on this investment which is quite high for certain investors.

Sum up

I decided to introduce this ETF because I consider that it is an interesting instrument where you can diversify your portfolio for a reasonable price. In my opinion, I consider this ETF suitable for medium-term or long-term investment. This sector has good fundamentals. Some of the main risks are the correlation with other markets, these companies operate globally so they can be affected by shocks around the world, they are adapting new technologies to their operations and the central banks' policy affects them directly.
Have a good trading!!


Disclaimer


I wrote this article myself, and it expresses my own opinions that shouldn't be used as a trading advice. Trading carries considerable risk due to the high leverage involved

Tuesday, 30 January 2018

FANG Stocks, tech portfolio

Everyone knows about the FANG stocks rally. But what does FANG mean? It’s a group of technology stocks, Facebook, Amazon, Netflix, and Google. If we look back to the beginning of 2015, we would regret not having invested in these stocks. Please bear in mind that it’s my first article using Python, so it can seem a little bit simple.


Stocks summary


Facebook

       Facebook stock, own elaboration with python and Quandl

Facebook is the biggest social network. It enables users to share opinions, ideas, photos, videos, and other activities online. It´s involved in the development of social media applications for people to connect through electronic devices. Its products include Facebook, Instagram, Messenger, WhatsApp, and Oculus. The revenue comes mainly from advertising.

Amazon

         Amazon stock, own elaboration with python and Quandl

It´s engaged in the provision of online retail shopping services  The efficiency of its distribution centers makes difficult to compete with Amazon. In addition, they have Amazon Web that it’s focused on the global sales of computing, storage, database, and AWS service offerings for start-ups, enterprises, government agencies, and academic institutions.

Netflix

        Netflix stock, own elaboration with python and Quandl

This company provides subscription service streaming movies and TV episodes over the Internet and sending DVDs by mail. Netflix obtains content from various studios and other content providers through fixed-fee licenses, revenue sharing agreements and direct purchases.

Google

        Google stock, own elaboration with python and Quandl

Alphabet operates as a holding company with interests in software, health care, transportation and other technologies. It operates through 2 segments: Google and Other Bets segments. The first one includes the following services: Search, Ads, Commerce, Maps, YouTube, Apps, Cloud, Android, Chrome, Google Play as well as hardware products, such as Chromecast, Chromebooks, and Nexus. The other one includes: as Access or Google Fiber, Calico, Nest, Verily, GV, Google Capital, X, and other initiatives.

Individual Stocks

At this point, I believe that you have your own preferences but let´s imagine that we are in 2015. Wouldn’t be better to create a portfolio with all of them?  Also, it´s another way to diversify our portfolio


    Log returns own elaboration using python

We can see how the individual stocks performed in the period. As you can see Netflix has been the more volatile. 


                                                                 Arithmetic Returns of the individual stocks

Google was the worst performer but it doubled in value. I would like to remind you that the Nasdaq index has returned 63% since 2015.
Before we put together all these stocks, let´s check the individual distributions:


             Log return distributions own elaboration

All of them have in common that the extreme observations are positive, which explains in part the reason of the rise in these stocks.

The Portfolio

After reviewing these companies and considering that they have different business units, we decide to create a portfolio. In order to make it simple, we can assign the same weight for each stock, in this case 25% of the initial capital. 

     Portfolio statistics and log returns distribution own elaboration

Considering the long run and this portfolio´ strategy (buy and hold), it´s easy to think that the majority of the daily returns are bigger than zero. This is confirmed by the chart above.
Is it safe to build a portfolio like we have done?  No, some of the reasons are that it´s not properly diversified and the correlation between the assets is positive. Luckily the companies have diversified some of their activities and they are heavily investing in technology which will bring revenue in the future. 
The portfolio return has been 104%.

                                                            Portfolio return own elaboration

Now it's the time to check the risk:

    Portfolio drawdown history, own elaboration

One of my favourites risk metrics is the drawdown. I created this chart showing the portfolio drawdown over the time. The maximum drawdown was 14.10%. This figure surprised me but the main concern is that the stock market raised on a daily basis

Sum up

I hope you like it. We have seen how the main tech portfolio has behaved since 2015. I wouldn’t invest in this kind of portfolio for the reasons mentioned above. In addition, I think that the index rally has been supported by an accommodative monetary policy. Using Python and Quandl has been great and I hope to bring more content in the future. Thanks.

Have a good trading!!


Disclaimer


I wrote this article myself, and it expresses my own opinions that shouldn't be used as a trading advice. Trading carries considerable risk due to the high leverage involved

#Alphabet #Amazon #drawdown #Facebook #FANG #Google #investing #maxdrawdown #Netflix #portfolio #python #quandl #stocks #Trading

8th day small profit that helps me to keep going in the competition

After a successful week and most importantly from recovering almost $6k, I wanted to consolidate my positive results. My desire was to b...